Although the WIP report is a standard operating and financial document construction companies must deal with, the landscape operator serious about growing their top line will end up dealing with it too. The WIP report is a formal financial document, standardized and outlined by ASC 606 (accounting standardization code) that influences many aspects of a successful business — or, if mishandled, can cause major strain on a business. Large construction projects require progress billing month to month, which means a report that shows the percentage of the job completed must be carefully managed each month.
What makes the WIP report as much operational as it is financial is the emphasis it places on projects managed well. Costs flow into the construction company in terms of, typically, five major categories: labor, materials, subcontractors, equipment, and other job costs. These costs flow in as operating costs, with field staff buying, managing, and transporting the items needed for the job. This operational behavior — getting what’s needed for jobs — impacts working capital, accounts payable, and DSO (days of sales outstanding) or AR (accounts receivable) aging. The men and women going about the work represent payroll: a weekly accrued cost, depending on how your company handles paycheck cadence.
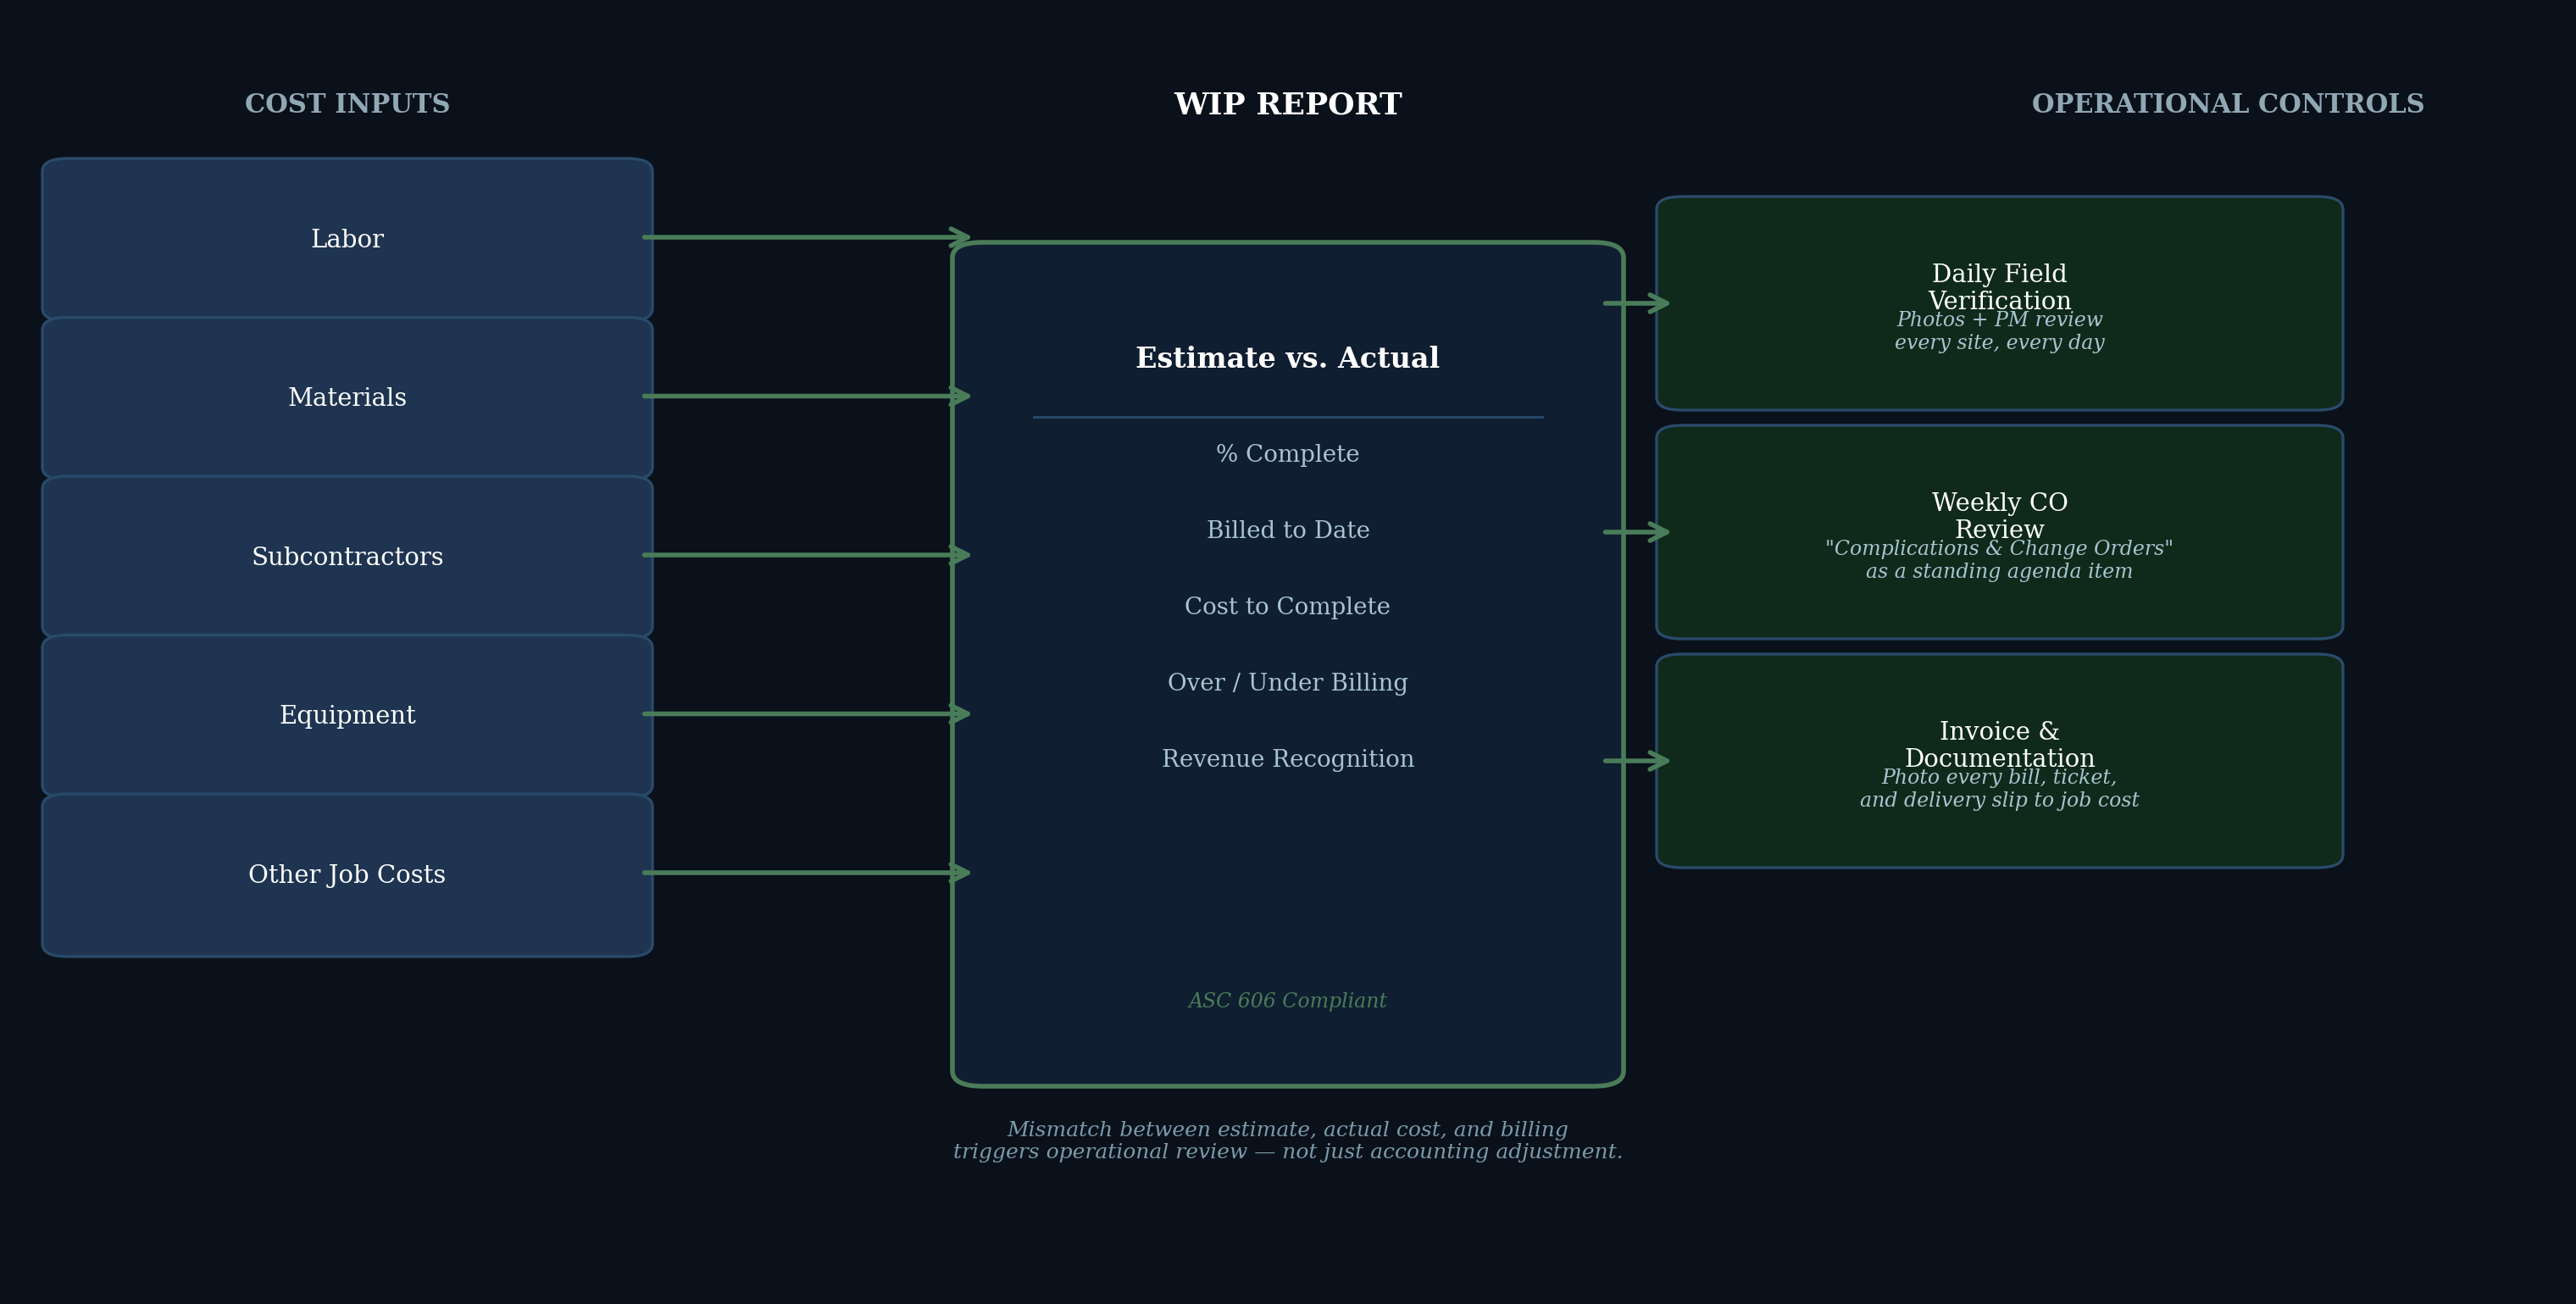
Cost inputs flow into the WIP report. Mismatches between estimate, actual cost, and billing trigger operational review — not just accounting adjustment.
The Estimate as a Diagnostic Tool
We need the estimates of the projects that make it onto the WIP report. This comparison of where projects stand relative to the estimate will generate important questions. To provide an example: if a sizable material purchase occurred out of the working capital account in the first week of the month, but the costs on that project do not reflect this material, we must ask questions and mitigate risk.
Assume for the moment that the material is not something typically treated as stored materials — that it only makes sense to the client that a material be bought if it will be used quickly after buying it.
The triangulation is straightforward: the estimate confirmed the material was needed. The bank account confirmed it was bought. Actual job costs do not show it. The questions that follow are both operational and financial. The recommendations that result require no complex accounting knowledge to understand or execute.
Three Recommendations
Daily Field Verification
Consider a daily field-verification recording and reporting system that project managers and superintendents review with the Director of Construction. Photos daily are required. This builds a record in real time, and a review of site conditions will inform whether the material should have been bought when it was.
Weekly Change Order Review
As part of the weekly operational meeting, build a dedicated agenda item: “Complications and Change Orders.” Keep it tight — a few minutes per project. Ask three questions: Do the parties involved on the project know about the complication? What is the rough financial impact? Are our records sufficient to justify a CO request?
Invoice and Documentation Policy
Implement a photo policy for every bill, delivery ticket, bill of lading, and invoice — with a dedicated submission location as a backup to project managers. This solves the costing gap, though it doesn’t solve whether we can bill for it this month. That second question impacts revenue this month and cash flow in the next 30 to 60 days. Both matter.
“The WIP report is only as good as the inputs feeding it, and those come from the field and those overseeing operations.”
These three recommendations will deliver different financial outcomes in time. We should not overlook change fatigue — ownership must understand that too much change too quickly will hurt both operations and the financials. All three of these recommendations grew out of looking at the WIP report, and they are decidedly operational. Finance professionals must be cautious about recommending policies that consume too much time of staff responsible for field execution. Getting costs in is imperative for billing, and billing is the lifeblood of a construction operation: without cash flow, everything the company does becomes more expensive.
The operators will produce what the WIP report visualizes and records. Operators drive the revenue engine. A seasoned financial leader will view it with the eyes of an operator.
Groundworks Consulting Group
Build the Financial Controls Behind Your Construction Operation
GCG works with landscape and construction operators on WIP management, job costing, change order capture, and the financial disciplines that protect margin from estimate to close. Start with the free assessment.
Take the Free Assessment